
Whereas the equity markets have recently been trading sideways at high levels amidst volatility, the fixed-income markets have come under increasing pressure in recent weeks. In the United States in particular, Treasury Secretary Scott Bessent is actively seeking to counter this trend. At the same time, rising energy prices and high public debt are bringing the debate on inflation and interest rates back into the spotlight.
“The House always wins” – In the casino, it’s clear who holds the upper hand. US Treasury Secretary Scott Bessent also appears to be seeking to apply this logic to the bond market at present. With the statement “I am the House now”, he is emphasising his determination not to stand idly by while yield pressures have recently been rising sharply, but to take proactive measures to counteract this situation. As the chart below shows, US interest rates have been rising steadily for years.
Note: Past performance is not a reliable indicator for future performance.
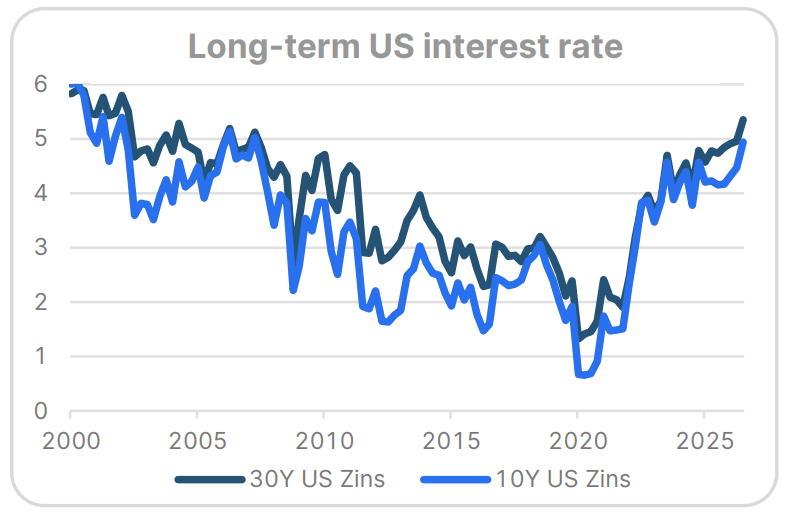
Recently, however, the momentum has accelerated significantly once again, meaning that the “magic threshold” of 5% for 30Y bonds has already been exceeded – a level last seen more than 20 years ago, before the financial crisis.
The powerful bond market is clearly giving the US government a warning – the national debt, which has been rising sharply for years, and above all the enormous refinancing costs, are putting US Treasury bonds – long the epitome of a safe haven – under considerable pressure. The US government could put a swift end to the rise in interest rates by adopting a more disciplined budget – but this is clearly not an option for Trump, and so Scott Bessent is taking on Wall Street. However, his latest announcement – to triple the US Treasury bond buyback programme to USD 6bn – has had no calming effect; on the contrary, interest rates are set to continue rising for the time being.
The oil price is also having a negative impact
Interest rates are not only rising in the USA; in Europe and Japan, too, we can see the highest levels in recent history. There is a certain contagion effect at play, but the situation is also linked to generally higher interest rate expectations. As expected, the ECB raised its key-lending rate to 2.5% in September, and further rate rises by the end of the year now appear entirely possible.
This is primarily due to the recent increase in energy prices and the associated inflationary concerns. Despite the upcoming US mid-term elections, the Iran conflict appears to be at an impasse, which means that the vital Strait of Hormuz remains closed. Even the most important alternative route via the Red Sea is likely to be increasingly at risk, now that the Iran-backed Houthi rebels have brought the coastal region of Yemen under their control.
We are therefore heading into the cold season with an oil price well above the key psychological threshold of USD 100. The situation on the European gas market is causing further unease. German gas storage facilities are at their lowest levels in 15 years, and the doubling of gas prices since June shows just how sensitively the market is reacting to potential supply bottlenecks. Should the coming winter turn out to be cold, conditions could become uncomfortable in more ways than just the weather.
Equities remain resilient
So far, the equity markets have remained surprisingly unfazed by rising interest rates and energy prices. Solid earnings and robust economic data continue to support share prices, although the headwinds are certainly growing.
Legal disclaimer
This document is an advertisement. Unless indicated otherwise, source: Erste Asset Management GmbH. The language of communication of the sales offices is German and the languages of communication of the Management Company also include English.
The prospectus for UCITS funds (including any amendments) is prepared and published in accordance with the provisions of the InvFG 2011 as amended. Information for Investors pursuant to § 21 AIFMG is prepared for the alternative investment funds (AIF) administered by Erste Asset Management GmbH pursuant to the provisions of the AIFMG in conjunction with the InvFG 2011.
The currently valid versions of the prospectus, the Information for Investors pursuant to § 21 AIFMG, and the key information document can be found on the website www.erste-am.com under “Mandatory publications” and can be obtained free of charge by interested investors at the offices of the Management Company and at the offices of the depositary bank. The exact date of the most recent publication of the prospectus, the languages in which the fund prospectus or the Information for Investors pursuant to Art 21 AIFMG and the key information document are available, and any other locations where the documents can be obtained are indicated on the website www.erste-am.com. A summary of the investor rights is available in German and English on the website www.erste-am.com/investor-rights and can also be obtained from the Management Company.
The Management Company can decide to suspend the provisions it has taken for the sale of unit certificates in other countries in accordance with the regulatory requirements.
Note: You are about to purchase a product that may be difficult to understand. We recommend that you read the indicated fund documents before making an investment decision. In addition to the locations listed above, you can obtain these documents free of charge at the offices of the referring Sparkassen bank and the offices of Erste Bank der oesterreichischen Sparkassen AG. You can also access these documents electronically at www.erste-am.com.
Our analyses and conclusions are general in nature and do not take into account the individual characteristics of our investors in terms of earnings, taxation, experience and knowledge, investment objective, financial position, capacity for loss, and risk tolerance. Past performance is not a reliable indicator of the future performance of a fund.
Please note: Investments in securities entail risks in addition to the opportunities presented here. The value of units and their earnings can rise and fall. Changes in exchange rates can also have a positive or negative effect on the value of an investment. For this reason, you may receive less than your originally invested amount when you redeem your units. Persons who are interested in purchasing units in investment funds are advised to read the current fund prospectus(es) and the Information for Investors pursuant to § 21 AIFMG, especially the risk notices they contain, before making an investment decision. If the fund currency is different than the investor’s home currency, changes in the relevant exchange rate can positively or negatively influence the value of the investment and the amount of the costs associated with the fund in the home currency.
We are not permitted to directly or indirectly offer, sell, transfer, or deliver this financial product to natural or legal persons whose place of residence or domicile is located in a country where this is legally prohibited. In this case, we may not provide any product information, either.
Please consult the corresponding information in the fund prospectus and the Information for Investors pursuant to § 21 AIFMG for restrictions on the sale of the fund to American or Russian citizens.
It is expressly noted that this communication does not provide any investment recommendations, but only expresses our current market assessment. Thus, this communication is not a substitute for investment advice.
This document does not represent a sales activity of the Management Company and therefore may not be construed as an offer for the purchase or sale of financial or investment instruments.
Erste Asset Management GmbH is affiliated with the Erste Bank and austrian Sparkassen banks.
Please also read the “Information about us and our securities services” published by your bank.