
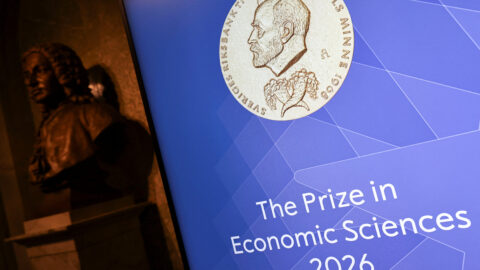
The 2026 Nobel Prize in Economics has been awarded to Robert E. Hall and Michael Woodford “for the microeconomic foundations of macroeconomic stabilization.” The award comes at just the right time: The AI investment boom is boosting economic growth and stock prices, while the conflict in the Middle East is driving up energy prices and weighing on the economy.
What is the basis of these two economists’ work, and why is it so relevant to the current economic situation?
Expectations determine consumption, demand, inflation, and interest rates
Hall demonstrated that households do not mechanically align their consumption with current income. The decisive factors are expected lifetime income, wealth, and the assessment of whether a shock is permanent or temporary. A temporary loss of real income—triggered, for example, by a rise in energy prices—can be cushioned by a lower savings rate. A permanent loss, on the other hand, is more likely to lead to an adjustment in consumption.
Woodford incorporated expectations into a standard model that is used today by economists worldwide: the New Keynesian model. Two key equations deserve special mention here.
The first part is the demand equation: Economic growth—or, more precisely, the output gap—depends on expected future economic growth and on the difference between the expected real policy rate and the natural real interest rate.
A real interest rate is the interest rate adjusted for inflation. The natural real interest rate, on the other hand, is a theoretical equilibrium rate at which the economy grows steadily. If the real policy rate is above the natural real interest rate, monetary policy has a restrictive effect: high interest rates dampen economic growth. If the real policy rate is below it, monetary policy stimulates demand: low interest rates support growth.
The second part is the inflation equation: Current inflation is influenced by expected future inflation and by economic growth—more specifically, by the output gap. Inflation expectations should not simply be equated with inflation forecasts. Companies take expected cost increases into account when setting their selling prices. The same applies to workers: When rents and energy prices rise, wage demands also increase.
If inflation expectations become unanchored, a temporary energy price shock can turn into a sustained inflationary process. If all participants in the economic process consistently expect higher inflation, inflation will actually rise. This is similar to the situation in a soccer stadium: if every spectator stands up to get a better view, no one ends up gaining anything. Applied to the economy, however, the price level has risen.
2026: A Boom in Demand Meets a Supply Shock
And this brings us to the current situation: In 2026, the global economy will be shaped by two opposing shocks. The AI boom is, at first, a positive demand shock that boosts economic growth. Investments in data centers, semiconductors, power grids, and digital infrastructure will bolster growth, exports, and production. At the same time, they will increase demand for capital, corporate profits, and stock prices. Because this stronger demand creates bottlenecks—for example, in semiconductors— inflationary pressure will also rise.
Only after some time could this lead to a positive supply-side effect through higher productivity gains. In this case, the potential average economic growth—that is, potential growth—would increase.
This is offset by a negative energy supply shock. The conflict with Iran has driven up the prices of oil, gas, and refined products. For energy consumers, this leads to a decline in real income because their costs are rising. Since economic value creation also depends on the conversion and use of energy, the price increase ultimately affects everyone, albeit to varying degrees.
In the October edition of the World Economic Outlook, the International Monetary Fund projects that global inflation will rise from 4.1% last year to 4.7% this year. A decline of 0.6 percentage points to 4.1% is expected for 2027. The figure for 2027 was raised from 3.9% to 4.1% compared with the July update. The inflation shock is thus greater than originally anticipated.
The energy shock is reducing real incomes and production potential, while higher inflation is necessitating a more restrictive monetary policy. For this reason, the International Monetary Fund expects global economic growth to slow from 3.5% last year to 3.1% this year. However, growth forecasts have been raised by 0.1 percentage points for the global economy and by 0.4 percentage points for advanced economies compared with last July’s estimates. This underscores the fundamental resilience of the global economy.
Note: Prognoses are not a reliable indicator of future performance.
Woodford’s model explains why weaker growth does not automatically call for interest rate cuts. A negative energy supply shock reduces production potential. Even with weaker actual growth, demand may remain too high relative to the reduced supply. The combination of higher inflation and weaker growth is therefore the typical hallmark of a negative supply shock.
Has the neutral real interest rate risen?
A rise in the natural real interest rate causes a given real policy rate to have a less restrictive effect. That is likely exactly what has happened this year. However, this cannot be determined with certainty because the natural real interest rate cannot be observed directly; it can only be estimated indirectly based on its effects.
The high demand for capital resulting from the AI boom has likely led to a rise in the natural real interest rate. Added to this are persistently high government deficits and the substantial capital requirements for infrastructure, defense, climate protection, climate change adaptation, and economic security.
As a result, central banks have come under pressure to raise key interest rates so that monetary policy continues to have the same effect on the economy. In other words, a rise in the neutral real interest rate has automatically made monetary policy more expansionary while key interest rates remain unchanged. Central banks responded with moderate increases in key interest rates, while the markets priced in expectations of higher key interest rates.
The main reason for the rise in yields and the resulting price declines in bonds this year was, in fact, the increase in yields on two-year bonds, which can be used as a proxy for expectations regarding key interest rates. Key interest rate expectations have since stabilized: two-year yields are no longer rising. At the same time, long-term yields have reached attractive levels, at least for investors with a long investment horizon.
As a general rule, the best time to invest in a particular asset class is often after significant price declines. This applies both to stocks—for which the most attractive entry point often occurs near the peak of a recession—and to bonds, which become more attractive again after a sharp rise in yields.
Please note: Investing in securities involves risks as well as opportunities.
Why Moderate Interest Rate Hikes Make Sense Right Now
The European Central Bank has raised its key interest rate this year from 2% to 2.5%. The U.S. Federal Reserve has raised its key interest rate from 3.75% to 4%. The market is pricing in about three more rate hikes for both central banks through September 2027.
A moderate and timely tightening of monetary policy can prevent the energy price shock from triggering lasting second-round effects through wages and longer-term inflation expectations. Monetary policy, however, cannot prevent the direct pass-through of higher energy costs to prices, for example through higher transportation costs.
By raising interest rates, central banks are credibly signaling their intention to meet the 2% inflation target. In doing so, they reduce the risk of having to respond much more forcefully later on and triggering a recession through massive interest rate hikes.
Moderate interest rate hikes do not necessarily lead to a decline in demand or economic growth. In fact, in their respective forecasts, central banks expect inflation to decline, but not economic output.
This does not mean that central banks should combat every rise in energy prices. Rather, the decisive factors are the duration of the shock, potential second-round effects in a tightening labor market, the strength of aggregate demand, and the fact that inflation has already been above the 2% target since 2021.
So far, the credibility of central banks has largely been maintained. In the U.S. and the euro area, short-term inflation compensation has risen in particular, while longer-term inflation expectations remain only slightly above the 2 percent target.
Implications for Asset Managers
Woodford’s model provides a clear analytical framework:
- Identify shocks, such as the AI boom and the energy crisis;
- Analyze their impact on the output gap, for example through the investment boom and the loss of real income;
- Determine the effects on the natural real interest rate, which has likely risen;
- Derive the central banks’ response in the form of interest rate hikes and fiscal policy measures in the form of government transfers;
- Then evaluate cash flows, discount rates, and risk premiums. Currently, very high earnings growth is offset by discount rates that have risen to a more appropriate level. Risk premiums, on the other hand, remain low.
A key lesson from the 2026 Nobel Prize in Economics is therefore this: It is not only the current levels of key interest rates, inflation, and income that are decisive for the economy and financial markets. It is also essential how households, businesses, and financial markets assess future developments. This includes, in particular, expectations regarding how real policy rates will evolve relative to the neutral real interest rate.
Legal disclaimer
This document is an advertisement. Unless indicated otherwise, source: Erste Asset Management GmbH. The language of communication of the sales offices is German and the languages of communication of the Management Company also include English.
The prospectus for UCITS funds (including any amendments) is prepared and published in accordance with the provisions of the InvFG 2011 as amended. Information for Investors pursuant to § 21 AIFMG is prepared for the alternative investment funds (AIF) administered by Erste Asset Management GmbH pursuant to the provisions of the AIFMG in conjunction with the InvFG 2011.
The currently valid versions of the prospectus, the Information for Investors pursuant to § 21 AIFMG, and the key information document can be found on the website www.erste-am.com under “Mandatory publications” and can be obtained free of charge by interested investors at the offices of the Management Company and at the offices of the depositary bank. The exact date of the most recent publication of the prospectus, the languages in which the fund prospectus or the Information for Investors pursuant to Art 21 AIFMG and the key information document are available, and any other locations where the documents can be obtained are indicated on the website www.erste-am.com. A summary of the investor rights is available in German and English on the website www.erste-am.com/investor-rights and can also be obtained from the Management Company.
The Management Company can decide to suspend the provisions it has taken for the sale of unit certificates in other countries in accordance with the regulatory requirements.
Note: You are about to purchase a product that may be difficult to understand. We recommend that you read the indicated fund documents before making an investment decision. In addition to the locations listed above, you can obtain these documents free of charge at the offices of the referring Sparkassen bank and the offices of Erste Bank der oesterreichischen Sparkassen AG. You can also access these documents electronically at www.erste-am.com.
Our analyses and conclusions are general in nature and do not take into account the individual characteristics of our investors in terms of earnings, taxation, experience and knowledge, investment objective, financial position, capacity for loss, and risk tolerance. Past performance is not a reliable indicator of the future performance of a fund.
Please note: Investments in securities entail risks in addition to the opportunities presented here. The value of units and their earnings can rise and fall. Changes in exchange rates can also have a positive or negative effect on the value of an investment. For this reason, you may receive less than your originally invested amount when you redeem your units. Persons who are interested in purchasing units in investment funds are advised to read the current fund prospectus(es) and the Information for Investors pursuant to § 21 AIFMG, especially the risk notices they contain, before making an investment decision. If the fund currency is different than the investor’s home currency, changes in the relevant exchange rate can positively or negatively influence the value of the investment and the amount of the costs associated with the fund in the home currency.
We are not permitted to directly or indirectly offer, sell, transfer, or deliver this financial product to natural or legal persons whose place of residence or domicile is located in a country where this is legally prohibited. In this case, we may not provide any product information, either.
Please consult the corresponding information in the fund prospectus and the Information for Investors pursuant to § 21 AIFMG for restrictions on the sale of the fund to American or Russian citizens.
It is expressly noted that this communication does not provide any investment recommendations, but only expresses our current market assessment. Thus, this communication is not a substitute for investment advice.
This document does not represent a sales activity of the Management Company and therefore may not be construed as an offer for the purchase or sale of financial or investment instruments.
Erste Asset Management GmbH is affiliated with the Erste Bank and austrian Sparkassen banks.
Please also read the “Information about us and our securities services” published by your bank.
More on the topic
Market Update: “Bond shock”
Interest rates are rising, the US midterms are approaching, and concentration risk is growing in the stock markets. Despite potential setbacks, however, the outlook for the fall stock market is positive. Read more in this discretionary portfolio management update from Gerald Stadlbauer.
Stock markets react volatile to tariff pause: what happens next?
The US government’s extensive tariff plans have been causing volatility on the stock markets since last week. Yesterday’s announcement of a 90-day pause for the new tariffs was met with relief by the markets – even though a further escalation between the US and China is on the horizon. We take a look at the current situation on the financial markets and analyse the possible consequences of an escalation in the trade conflict.