
Why the sell-off is hitting high expectations the hardest, and what signals the bond market is sending
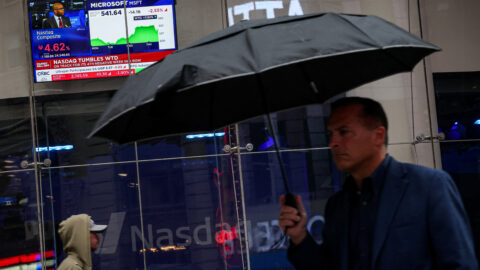
The recent market turmoil is a stress test for AI euphoria. Following the US midterm elections, technology and semiconductor stocks in particular came under pressure. Behind this are two interconnected questions: Will the billions invested in data centers generate sufficient returns? Could new political hurdles delay or increase the cost of expansion?
So far, the US bond market has not signaled a comparably pronounced flight into a recession scenario. The correction therefore points more toward a reassessment of ambitious growth expectations than toward an already broadly priced-in economic downturn.
Please note: Past performance is no reliable indicator of future value development.
Market developments in the week through November 6, 2026
- Nasdaq 100: −6.2 percent
- US technology sector: −9.5 percent
- 10-year US Treasury yield: −10 basis points
Source: Bloomberg market overview provided
The sell-off is hitting the AI winners the hardest
The S&P 500 lost around 4.4 percent in yesterday’s trading session. The decline in the technology sector was considerably steeper. The Nasdaq 100 fell 6.2 percent over the week, and the US technology sector dropped 9.5 percent. Losses at chipmakers Nvidia and AMD were even more pronounced. Asian markets also came under pressure, as numerous chip and hardware manufacturers depend on the continued expansion of US computing infrastructure.
Please note: The companies mentioned in this article have been selected as examples and do not constitute investment recommendations.
While the price decline is broadly visible, its epicenter lies among companies whose valuations depend especially heavily on future earnings from AI expansion. This is what currently distinguishes the move from a classic recession shock.
A sharp price decline is not automatically evidence of weak business performance. For highly valued growth companies, a large part of today’s enterprise value rests on profits expected only years from now. If discount rates rise or assumptions about growth, margins, and long-term returns on capital are lowered, fair value can fall significantly even if revenues and profits continue to grow in the near term.
Concentrated positioning, weakening technical trends, and rising risk aversion may also have amplified the move. The extent to which systematic strategies, derivatives positions, or forced risk reductions contributed to the sell-off cannot be determined without reliable, up-to-date positioning data.
From investment promises to measurable returns
The major US technology companies are investing in chips, data centers, networks, and power supply on an unprecedented scale. Based on current plans and estimates, capital expenditure by Microsoft, Alphabet, Amazon, Meta, and Oracle could reach around 803 billion US dollars in 2026. These figures reflect management plans and estimates, not spending already realized for the full year.
For semiconductor, server, and infrastructure manufacturers, these investments are already translating into revenue today. For the buyers, however, the result is assets that must generate sufficient income over many years to cover acquisition, operation, financing, and economic depreciation. High chip sales are therefore not equivalent to a guaranteed return for the AI ecosystem as a whole.
This shifts the central valuation question. So far, the market has mainly rewarded rising investment budgets and the rapid buildout of computing capacity. Going forward, what is likely to matter more is whether this translates into corresponding revenues, free cash flow, and attractive returns on capital.
This development fits the concept of an S-curve. After a phase of accelerated growth, investment and profits can continue to rise, but at declining growth rates. That would not yet constitute a contraction. For highly valued stocks, however, such a slowdown can still have significant consequences if prices have already priced in continued acceleration.
Parts of the AI ecosystem may therefore well show signs of excess. These include the extrapolation of exceptionally high growth rates, concentrated positioning, and dependence on continuously rising investment. However, this does not mean that artificial intelligence is merely a speculative bubble or that the entire technology sector is overvalued. The leading technology companies are profitable, generate high cash flows, and largely have solid balance sheets. A fundamental technological innovation and the overvaluation of individual companies can coexist.
Productivity: initial effects, but no AI boom yet
US productivity data provide initial evidence that digitalization, automation, and possibly artificial intelligence are boosting economy-wide efficiency. Non-farm output rose by 2.3 percent in the third quarter of 2026, while hours worked increased by only 0.2 percent. Output per hour worked thus rose by 2.1 percent. Nearly all of the output growth was therefore driven by higher labor productivity rather than by additional labor input.
This is economically significant. The US economy is producing more without expanding labor input to a comparable degree. However, the aggregated data do not allow the specific contribution of artificial intelligence to be isolated. Conventional software, automation, higher capital intensity, changes in employment structure, and cyclical factors can also affect productivity.
Moreover, the quarterly trend shows no further acceleration. Productivity growth slowed from 2.8 percent in the first quarter to 2.3 percent in the second and 2.1 percent in the third quarter. The data are more consistent with an early diffusion phase, in which initial efficiency gains become visible, than with an already pronounced AI-driven productivity boom.
Higher productivity is at least easing labor cost pressure. Compensation per hour worked rose by 4.5 percent in the third quarter, while unit labor costs increased by only 2.4 percent. Outside of labor costs, however, pressure remains high. Non-labor payments per unit of output rose by 6.0 percent. The buildout of computing infrastructure could be contributing to this through depreciation, financing, and energy costs. How large this effect actually is cannot be determined from the aggregated data.
AI could therefore already be improving labor productivity while simultaneously driving up capital and infrastructure costs. For companies and investors, what ultimately matters is whether long-term gains in productivity and earnings outweigh the full cost of capital deployed.
Political uncertainty raises the risk
The Democrats’ success in the midterm elections raises the prospect of stronger parliamentary oversight and stricter requirements for the AI industry. Of particular relevance are possible hurdles to building new data centers: permitting processes, power and water consumption, grid connections, and resistance at the state and local level. Such requirements could delay projects and increase their costs.
However, political uncertainty is not yet enacted regulation. Starting in January 2027, a Democratic-controlled Congress will face a Republican president. Federal legislation is therefore likely to remain contested. For individual projects, decisions by states and municipalities could have a more immediate impact.
The elections were thus a plausible catalyst, but not the sole cause of the sell-off. The market is reacting to a higher probability of delays and rising costs, not to already enacted restrictions on AI expansion.
The bond market is not yet signaling a recession
In a broad economic shock, investors would typically not only sell stocks but also expect significantly stronger key rate cuts. This reaction is barely visible so far. Yields on two-year US Treasuries fell by 12 basis points, 10-year yields by 10, and 30-year yields by 6 basis points. The move is noticeable but moderate relative to the equity sell-off. The 10-year US Treasury yield most recently stood at around 4.83 percent.
The futures market also currently shows no sign of imminent monetary easing. For the meeting on December 9, model-based estimates put the probability of a 25 basis point rate hike at around 66 percent. Such probabilities can change quickly. However, the current reading argues against the notion that the market is already pricing in a significant economic downturn or rapid monetary easing (source: Bloomberg).
A broader recession signal would require additional developments: markedly rising credit risk premiums outside the AI sector, a pronounced weakening of the labor market and consumer spending, and widespread downward revisions to earnings expectations in sectors without an AI focus.
Implications for equity allocation
Our tactical allocation at the start of the month (before the price declines) already reflects a reduction in risk. The broad US equity position was scaled back from around 67 to 43 percent. Within the US, selective positions in Quality, Information Technology, Health Care, and High Dividend remain in place. This preserves exposure to structural growth while placing greater emphasis on profitable companies, robust balance sheets, and actual free cash flow generation.
Broader regional diversification across Europe, Japan, Asia ex-Japan, and Latin America reduces reliance on US mega-cap technology. The position in global metals and mining companies adds a real-economy investment component to the portfolio. This diversification does not protect against a global rise in risk aversion, but it does reduce concentration risk should the correction primarily affect highly valued US growth stocks.
Conclusion
The stock market is currently putting the pace and economics of AI expansion back up for debate. The US elections are adding to uncertainty but do not alone explain the sell-off. At the same time, the productivity data provide early signs of real efficiency gains, without yet confirming an accelerated AI boom.
The technological breakthrough is therefore not disproven. However, the bar for valuation, balance sheet quality, free cash flow, and return on capital is rising noticeably. So far, the bond market points more toward a reassessment of growth and valuation risks than toward a broadly priced-in recession.
What matters now are earnings revisions, the investment plans of major cloud providers, order intake in the semiconductor industry, data center utilization, the conversion of profits into free cash flow, and the development of credit spreads and market breadth. Until these indicators provide a clearer picture, discipline and diversification make more sense than hectic reactions to individual trading days.
Note: Investment in securities entail risks in addition to the opportunities described.
Legal disclaimer
This document is an advertisement. Unless indicated otherwise, source: Erste Asset Management GmbH. The language of communication of the sales offices is German and the languages of communication of the Management Company also include English.
The prospectus for UCITS funds (including any amendments) is prepared and published in accordance with the provisions of the InvFG 2011 as amended. Information for Investors pursuant to § 21 AIFMG is prepared for the alternative investment funds (AIF) administered by Erste Asset Management GmbH pursuant to the provisions of the AIFMG in conjunction with the InvFG 2011.
The currently valid versions of the prospectus, the Information for Investors pursuant to § 21 AIFMG, and the key information document can be found on the website www.erste-am.com under “Mandatory publications” and can be obtained free of charge by interested investors at the offices of the Management Company and at the offices of the depositary bank. The exact date of the most recent publication of the prospectus, the languages in which the fund prospectus or the Information for Investors pursuant to Art 21 AIFMG and the key information document are available, and any other locations where the documents can be obtained are indicated on the website www.erste-am.com. A summary of the investor rights is available in German and English on the website www.erste-am.com/investor-rights and can also be obtained from the Management Company.
The Management Company can decide to suspend the provisions it has taken for the sale of unit certificates in other countries in accordance with the regulatory requirements.
Note: You are about to purchase a product that may be difficult to understand. We recommend that you read the indicated fund documents before making an investment decision. In addition to the locations listed above, you can obtain these documents free of charge at the offices of the referring Sparkassen bank and the offices of Erste Bank der oesterreichischen Sparkassen AG. You can also access these documents electronically at www.erste-am.com.
Our analyses and conclusions are general in nature and do not take into account the individual characteristics of our investors in terms of earnings, taxation, experience and knowledge, investment objective, financial position, capacity for loss, and risk tolerance. Past performance is not a reliable indicator of the future performance of a fund.
Please note: Investments in securities entail risks in addition to the opportunities presented here. The value of units and their earnings can rise and fall. Changes in exchange rates can also have a positive or negative effect on the value of an investment. For this reason, you may receive less than your originally invested amount when you redeem your units. Persons who are interested in purchasing units in investment funds are advised to read the current fund prospectus(es) and the Information for Investors pursuant to § 21 AIFMG, especially the risk notices they contain, before making an investment decision. If the fund currency is different than the investor’s home currency, changes in the relevant exchange rate can positively or negatively influence the value of the investment and the amount of the costs associated with the fund in the home currency.
We are not permitted to directly or indirectly offer, sell, transfer, or deliver this financial product to natural or legal persons whose place of residence or domicile is located in a country where this is legally prohibited. In this case, we may not provide any product information, either.
Please consult the corresponding information in the fund prospectus and the Information for Investors pursuant to § 21 AIFMG for restrictions on the sale of the fund to American or Russian citizens.
It is expressly noted that this communication does not provide any investment recommendations, but only expresses our current market assessment. Thus, this communication is not a substitute for investment advice.
This document does not represent a sales activity of the Management Company and therefore may not be construed as an offer for the purchase or sale of financial or investment instruments.
Erste Asset Management GmbH is affiliated with the Erste Bank and austrian Sparkassen banks.
Please also read the “Information about us and our securities services” published by your bank.
More on the topic
Five years since Covid hit: a historic crash, and the lessons learned
This week marks the fifth anniversary of the low point of the coronavirus crash. In February and March 2020, global financial markets experienced one of the fastest downturns in history. The coronavirus crisis brought the economy to a virtual standstill and caused a massive decline in stock prices, unsettling many investors.
Our new blog post looks back at the events that led to this crash and analyses what lessons investors can learn from the Covid crash. Because as quickly as prices fell, they were also largely able to recover the losses.
Pharmaceutical Companies Increase Sales, Focus on Innovation and Acquisitions
The pharmaceutical industry was able to further increase its sales in the last quarter. The biggest players in the sector are relying on acquisitions and innovations – including the increased use of AI. However, things could get more uncomfortable for pharmaceutical companies in the US market: the future US Secretary of Health and Human Services, Rober F. Kennedy Jr., is considered a critic of the industry and has already spoken out in favor of capping drug prices.